Step 2 · Pre-approval
 MODY IBRAHIMRE/MAX Realty Professionals
Sign inJoin freeSign in to save across devices.Saving to your account…Saved to your accountAnother device changed your saves. Review the latest account state and try again.Could not sync this change. Please try again.This search is too long to save. Remove some choices, then try again. Your current filters are kept.Name this saved searchUse one of your saved searchesChoose a saved search (optional)Save search to your accountKeep your searches and favourite homes across devices with a free Mody account. Your request is already saved; joining is optional.Keep exploring with a free account.You’ve reached this browser’s guest search allowance. Join free for unlimited property searches, saved homes and searches, and your email-alert preferences.Join free for unlimited searchesYour free Mody accountSaved-search preferencesReview these preferences before sending. The request does not create an automatic subscription.Your existing answers were kept. Add any saved preferences you want Mody to receive.This search has too many combined choices to save. Remove some filters, then try again. Your current filters are kept.These filters could not be checked, so this search was not saved. Keep your choices and try again.
Explore with Cal
Three taps, and Cal shows you communities that fit the way you live.
Nearby communities
Buyer Resource Centre · Step 1 · Get ready
Your credit history helps a lender decide whether to approve your mortgage, which rate to offer and how much to lend. Here is how credit scores work in Canada, what lowers them, and what you can do before you apply.
Key takeaways
Canadian rules in this article reviewed October 21, 2026. General information, not personal advice.
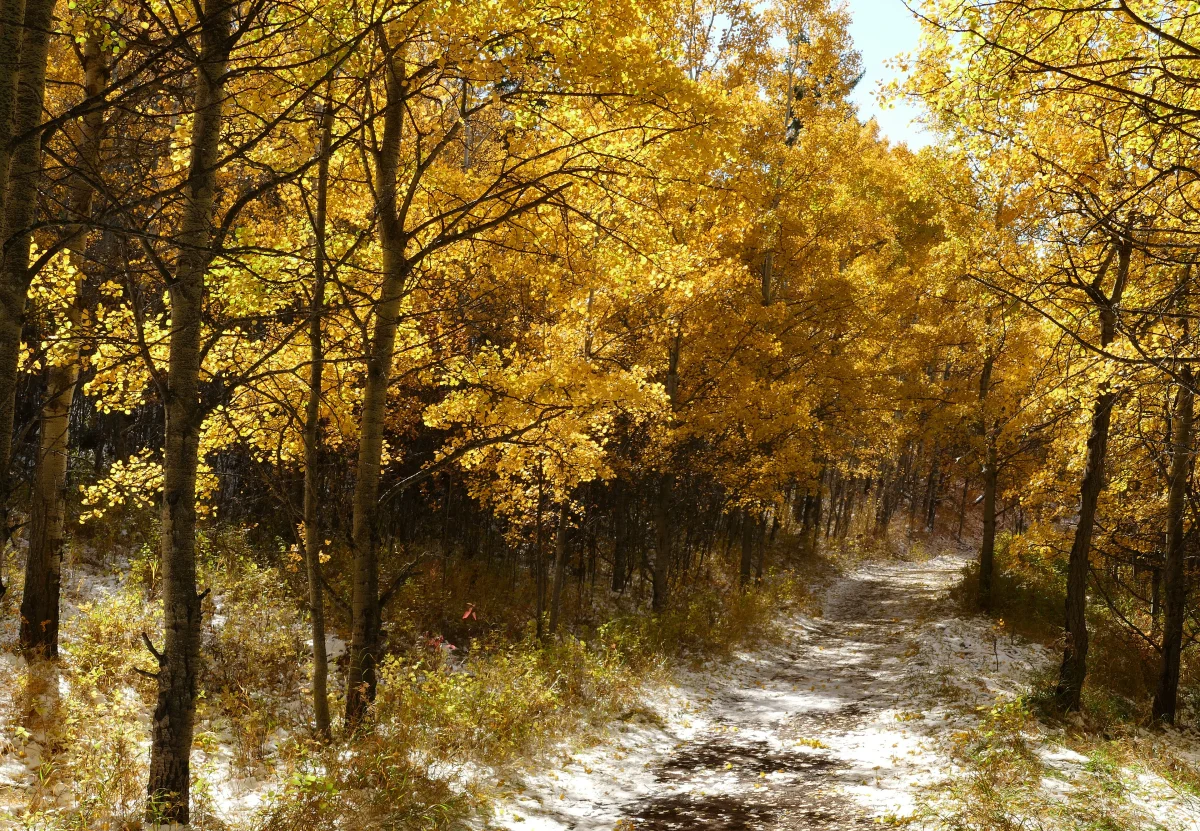
Photo: Edworthy Park, Calgary. Daniel (daniel0685), Wikimedia Commons, CC BY 2.0.
A credit score is a three-digit number, worked out from your credit report, that sums up how you have handled borrowing. Canada has two national credit bureaus, Equifax Canada and TransUnion Canada. Each keeps its own report on you, and their scores usually run from 300 to 900.1
You may read that scores run from 300 to 850: that is the range of base FICO® scores in the United States.2 The two Canadian bureaus’ reports can differ, so check both.
Your score is shaped by:
A stronger credit history can help you qualify with more lenders, at better rates and on better terms. A lower score does not always mean no, but it can narrow your choices: you may be offered a higher rate, asked for more documents, or pointed to lenders that charge more.
If you put down less than 20%, you will typically need mortgage default insurance. CMHC requires at least one borrower (or guarantor) to have a credit score of at least 600.3
Your score is only part of the picture. Lenders also look at your income, your other debts, your down payment and whether you pass any required stress test. The home price sets the published minimum down payment. A lender may ask for more, for example if you’re self-employed or have a poor credit history.6
Try it with your numbers
See how the stress test and your other debts shape what a lender may lend. It opens with today’s qualifying-rate rule built in.
Talk to a lender or mortgage broker early. A pre-approval reviews your credit and tells you where you stand. Then, until your purchase closes, avoid new credit, large purchases on credit and job changes without speaking to your lender first.
From Mody
Planning to buy a home? Understanding your credit profile early can help you prepare for mortgage approval. Contact Mody Homes to discuss your next steps.
Mody confirms a time with you. Sending a request books nothing until he replies.
Keep reading
Step 2 · Pre-approval
Step 5 · Close
Your city. Your story. Your next chapter.
Talk to Mody about your home purchase.
Educational information only
The articles, checklist and calculators in the Buyer Resource Centre are general educational information for buyers in Alberta. They are not a substitute for personalized legal, financial, mortgage, tax or property inspection advice, and they never guarantee mortgage approval or savings. Rules and rates change: each article shows when its rules were last reviewed. Mody Ibrahim is a REALTOR® with RE/MAX Realty Professionals; he is not a lender, mortgage broker, lawyer or home inspector.