Step 2 · Pre-approval
 MODY IBRAHIMRE/MAX Realty Professionals
Sign inJoin freeSign in to save across devices.Saving to your account…Saved to your accountAnother device changed your saves. Review the latest account state and try again.Could not sync this change. Please try again.This search is too long to save. Remove some choices, then try again. Your current filters are kept.Name this saved searchUse one of your saved searchesChoose a saved search (optional)Save search to your accountKeep your searches and favourite homes across devices with a free Mody account. Your request is already saved; joining is optional.Keep exploring with a free account.You’ve reached this browser’s guest search allowance. Join free for unlimited property searches, saved homes and searches, and your email-alert preferences.Join free for unlimited searchesYour free Mody accountSaved-search preferencesReview these preferences before sending. The request does not create an automatic subscription.Your existing answers were kept. Add any saved preferences you want Mody to receive.This search has too many combined choices to save. Remove some filters, then try again. Your current filters are kept.These filters could not be checked, so this search was not saved. Keep your choices and try again.
Explore with Cal
Three taps, and Cal shows you communities that fit the way you live.
Nearby communities
Buyer Resource Centre · Step 5 · Close
Extra payments, made early and often, can take years off a mortgage and save a large amount of interest. Here is how each strategy works, an example worked out month by month, and what to check with your lender first.
Key takeaways
Canadian rules in this article reviewed October 21, 2026. General information, not personal advice.
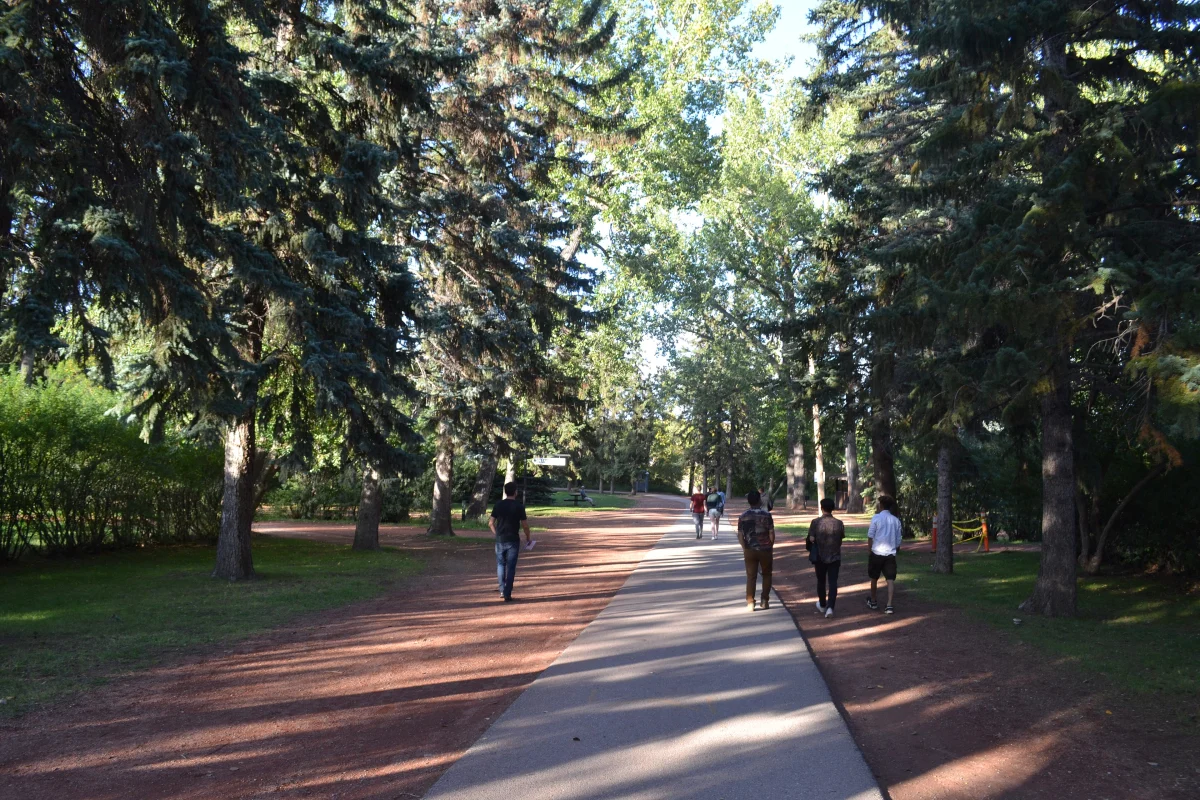
Photo: autumn in Alberta. Bernard Spragg, Wikimedia Commons, CC0.
Each payment first covers the interest owed since the last one; the rest pays down what you owe, the principal. In the early years most of each payment is interest. Anything extra goes straight to the principal, so the next interest charge is a little smaller, and so is every one after it.
The example on this page assumes a fixed rate, with interest calculated half-yearly, not in advance, as Canadian law allows for mortgages with blended payments.1
Rounding your payment up, even by a small amount, adds up over the years.
A tax refund, a bonus or other savings can go straight to the principal. Your mortgage agreement says whether you can make lump-sum payments, how much, and on which dates.2
The earlier in the mortgage you make a lump-sum payment, the more interest it saves, because it lowers the balance that interest is charged on for longer.
The amortization is the total time it takes to pay off the mortgage. A shorter amortization means higher regular payments but much less interest.
A longer amortization with voluntary extra payments keeps your required payment lower if money gets tight, but it only saves interest if you actually make the extra payments.
Before you pay extra, check your mortgage agreement or ask your lender:
Example · how it was worked out
Example · A
Example · B
Example · C
Example · D
In this example, rounding up to $3,000 saves about $24,935 and ends the mortgage 1 year, 5 months sooner. Paying $5,000 once a year saves about $86,595, a little more than a 20-year amortization, while the required payment stays at $2,908.02.
Example only, worked out month by month with the assumptions above, by the same engine as the Extra payments calculator. It is not a quote, a prediction or a promise of savings.
Try it with your numbers
Opens with this example filled in. Change any number to see your own result.
From Mody
Want to understand your mortgage options? Contact Mody Homes for guidance as you plan your next home purchase.
Mody confirms a time with you. Sending a request books nothing until he replies.
Keep reading
Step 2 · Pre-approval
Your city. Your story. Your next chapter.
Talk to Mody about your home purchase.
Educational information only
The articles, checklist and calculators in the Buyer Resource Centre are general educational information for buyers in Alberta. They are not a substitute for personalized legal, financial, mortgage, tax or property inspection advice, and they never guarantee mortgage approval or savings. Rules and rates change: each article shows when its rules were last reviewed. Mody Ibrahim is a REALTOR® with RE/MAX Realty Professionals; he is not a lender, mortgage broker, lawyer or home inspector.